Five Years of Levelling Up: The Schemes That Delivered, and the Renders on the Hoarding
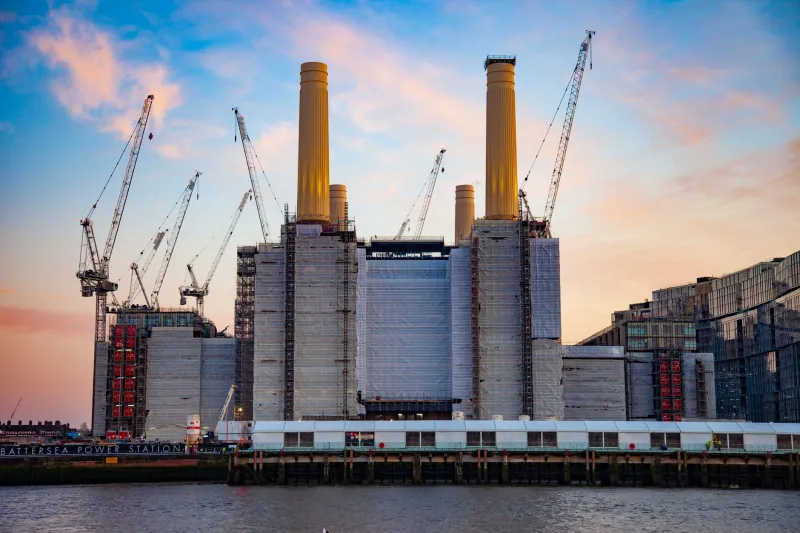
It has been long enough now to judge. The levelling-up agenda — with its Town Deals, Future High Streets Fund awards and the eponymous Levelling Up Fund — promised to redistribute growth capital to the places the market had forgotten. Five years in, the honest answer is that it has done both exactly that and very much less, and the divergence between the two outcomes tells developers more than any press release.
What Has Actually Worked
The schemes that delivered share a common architecture: a single accountable delivery vehicle, a plausible private-sector co-investor, and a project that was 'shovel-ready' in fact rather than in presentation.
The clear winners tend to be towns that received funding as an accelerant to momentum rather than a substitute for it. Places such as Stoke-on-Trent, Sunderland and parts of the South Wales Valleys used public capital to de-risk sites and fund enabling infrastructure, pulling private residential and commercial schemes forward that were already circling. In those postcodes, the needle has moved — not dramatically, but measurably: site values up, vacancy rates down, and a pipeline of consents that would not otherwise exist.
Mayoral development zones in combined-authority areas have generally outperformed too, principally because decisions sit closer to the ground and delivery vehicles persist beyond electoral cycles.
The Renders on the Hoarding
The failures are equally patterned. Where funding was allocated on the basis of bid-writing capability rather than delivery capacity, hoardings have aged gracefully around schemes that never secured a developer. The recurring symptoms are familiar:
- Masterplans commissioned without a delivery partner or an identified occupier.
- Capital allocated for capital works, with nothing for the revenue costs of management and curation.
- Political timelines dictating spend deadlines that forced poor early decisions.
The uncomfortable conclusion is that regeneration funding does not create markets. It can only amplify them, or — where no underlying demand exists — prolong the appearance of activity while the fundamentals stagnate.
The Watchlist
For investors and developers with patience, the interesting question is where the next phase of capital is quietly landing. Three patterns merit attention.
Second-round levelling-up towns. The final funding rounds allocated capital to smaller places that learned from the first wave's mistakes — more modest schemes, clearer delivery routes. Watch the market towns of the East Midlands and the coastal centres of the North East.
Transport-anchored schemes. Where regeneration funding intersects with committed rail investment — notably around stations on reopened lines and upgraded corridors — the case is materially stronger than where the two run in parallel.
Purple-flag evening economies. Towns that invested in night-time and cultural infrastructure, rather than retail alone, are showing more resilient footfall. The high street of 2030 will not be saved by shops.
The Verdict
Levelling up neither failed nor succeeded; it sorted. It sorted places with delivery capacity from places without it, and sorted developers who understood public-capital leverage from those who waited for certainty that never comes. Five years on, the lesson for the next agenda — whatever it is called — is that the money was never the hard part. The delivery was.